Mortgage guidance built around your goals.
Know what you’re comfortable spending before you start house hunting.
Serving Northwest Ohio and Southeast Michigan, I start every mortgage with a conversation about what you’re trying to accomplish, not an application.
I’ll explain your options, recommend a strategy and share the why behind it, so you can decide with confidence.
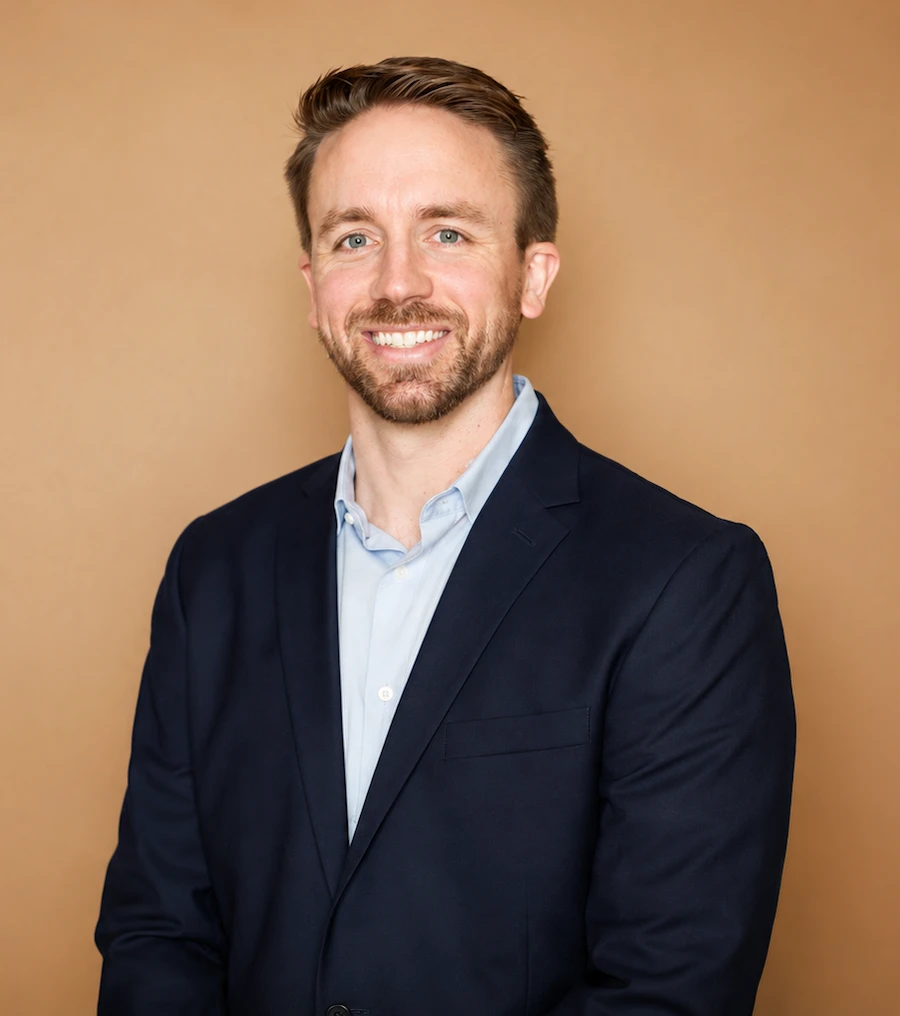
Drew Messer
Senior Loan Officer · NMLS #2186567
5 Years
in Mortgage Lending
Operations Experience
Production and Operations Management Background
Fully Underwritten
Pre-Approvals Available
As Little as 2 Weeks
For Qualified Closings
Closing timelines vary by borrower and transaction.
How can I help?
Different goals require different strategies.
Your income, timeline and plans all matter. Let’s start with what you’re trying to accomplish.
Honest pricing
The lowest rate isn’t always the best option.
A low rate can come with discount points, which are upfront fees you pay in exchange for a lower interest rate. Sometimes that’s a smart trade. Whether it makes sense depends on how long you expect to keep the loan.
I’ll show you the options side by side and explain what each one costs. And if another lender has the better deal, I’ll tell you.
I like to be able to sleep at night.
What I compare with you
Interest rate
The number in the ad is only one part of the price.
Points and fees
Discount points are upfront costs paid to lower the rate.
Monthly payment
What you'll actually pay each month.
Cash to close
What you need to bring to the closing table.
Time you keep the loan
Whether paying upfront for a lower rate has time to pay off.
What clients say
Communication matters.
Drew was the perfect mortgage lender to work with as a first time homebuyer. He explained everything and was constantly giving us updates throughout the process. Also when questions arose Drew would pick up the phone quickly! 10/10 recommend!!
Bailey Kayne · Google review Drew was great to work with! Very personable and always willing to answer questions. Definitely recommend!
Sarah Ellis · Google review I had a great experience working with Drew. The process was smooth and efficient, a quick appraisal turnaround and great communication from start to finish.
Catherine S · Google review
Reviews from Google.
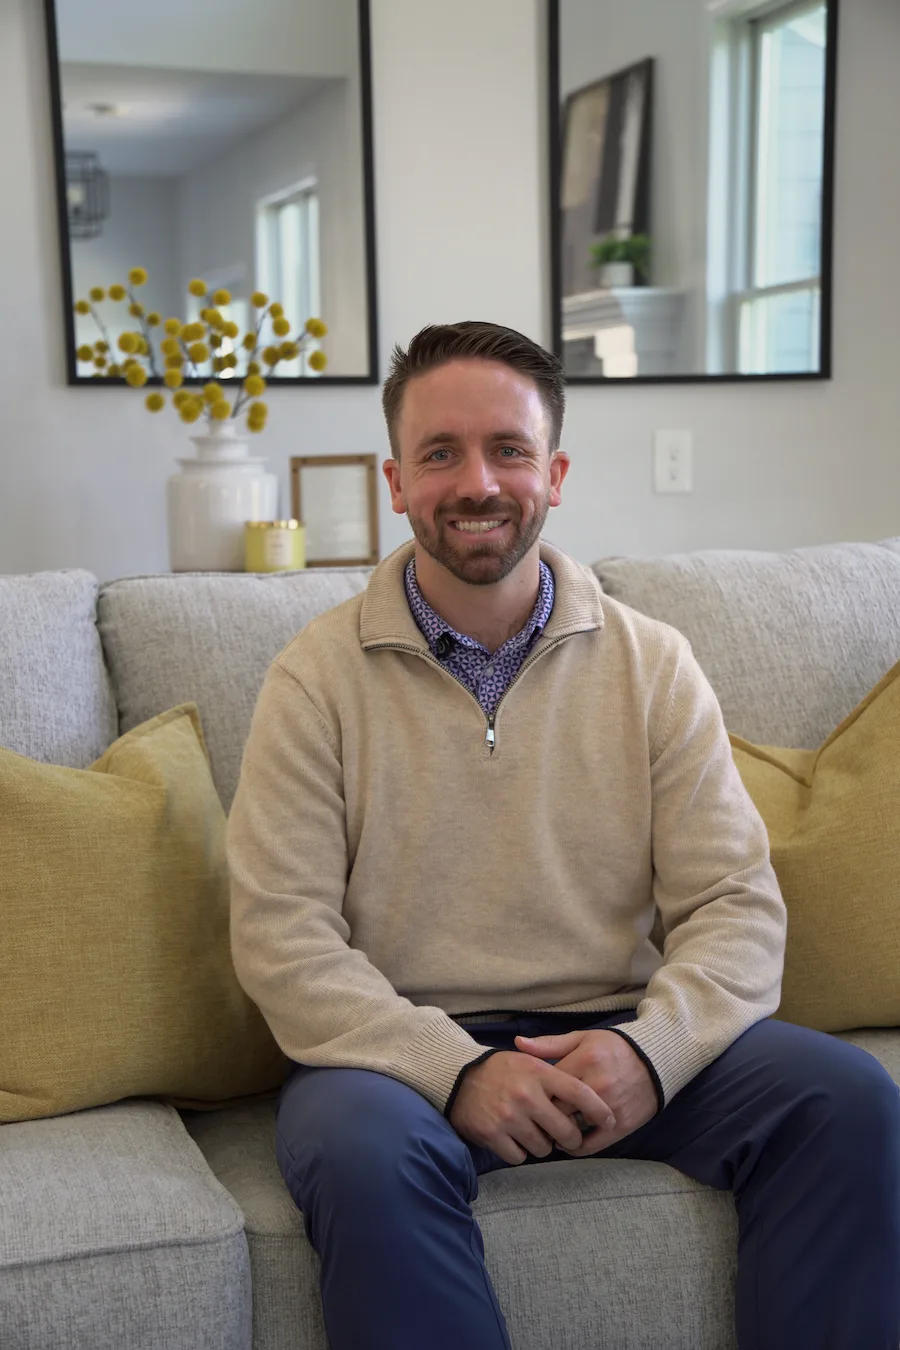
Meet Drew
Calm guidance. Experience behind it.
Before mortgages, I spent five years as an occupational therapist in a Level I trauma hospital, including the ICU and burn unit. That experience taught me to stay calm and explain complicated things clearly.
I then worked in mortgage production and operations. Today I bring that experience directly to borrowers, looking for potential issues early and making sure you understand your options.
The process
A clear process from the first conversation to the closing table.
Step 1: Start with a conversation
Before any application, I want to understand your budget, income, timeline and what you're trying to accomplish.
Step 2: Compare options and get prepared
We'll compare costs side by side and I'll tell you what I recommend and why. When it makes sense, we'll review documents and work toward a pre-approval, which is still subject to final conditions.
Step 3: Move toward closing
Once you're under contract, I'll coordinate through underwriting, keep you updated on conditions and help you get to the closing table.
Another perspective
Been told no? Let’s take another look.
A decline from one lender doesn’t necessarily mean there isn’t another option.
Different lenders have different programs, guidelines and ways of approaching complicated scenarios. If your financing doesn’t fit neatly into the conventional box, I’m happy to take a second look.
Not every scenario will qualify. A review of your individual circumstances is required.
Another lender’s answerdoesn’t have to bethe final answer.
For Realtors
Your lender should help protect the transaction.
A pre-approval letter doesn’t mean much if the work behind it wasn’t thorough.
I approach Realtor partnerships with the same mindset I learned in mortgage operations: identify potential problems early, communicate clearly and get the transaction to the closing table.
Fully Underwritten Pre-Approvals
For qualified borrowers, we can take the process beyond a traditional pre-approval and obtain underwriting review before the buyer is under contract, helping create a stronger, more reliable offer.
Fast Closings
When timing matters, qualified transactions may be able to close in as little as two weeks.
Problem-Solving Experience
Complicated income, self-employed borrowers and scenarios that don't fit neatly into traditional guidelines deserve a closer look, not an automatic no.
Second Opinions
Have a buyer whose financing hit a roadblock? I'm happy to review the scenario and see whether another option exists.
Borrower stories
How I’ve helped borrowers.
A Veteran's Path to Homeownership
He wasn't ready to qualify when we first spoke. We put a plan together, and he followed it. About ten months later he was preapproved, and he and his family went on to become homeowners.
Read the Story12 Days and Nowhere Else to Go
A client was moving between states and living in an Airbnb when he went under contract. He needed to be out in 12 days. We knew the timeline from the beginning, moved quickly and were clear to close ahead of schedule.
Read the StoryWhen Two Banks Said No
A self-employed borrower had significant business write-offs and had already been declined by two banks. Traditional documentation wasn't telling the whole financial story. Using a bank-statement loan, we found another way to document qualifying income and helped the borrower purchase the new home.
Read the Story
These stories illustrate individual borrower experiences. Loan approval, program eligibility and results vary based on individual circumstances.
Mortgage education
Understand the mortgage, not just the payment.
I believe borrowers make better decisions when they understand their options. Explore straightforward answers to common mortgage questions without the unnecessary jargon.
Do You Really Need 20% Down?
No. Here's where that misconception comes from and what buyers should actually understand about down payments.
Get the AnswerFHA vs. Conventional
Neither is automatically “better.” Here's how I think about the decision.
Get the AnswerHow Do Bank Statement Loans Work?
A different way for some self-employed borrowers to document qualifying income.
Get the AnswerIs PMI Really a Bad Thing?
Mortgage insurance is a cost to understand, not a reason to dismiss an otherwise useful option.
Get the AnswerPre-Qualification vs. Pre-Approval
The strength of a letter depends on the work behind it, not just the label at the top.
Get the AnswerCan I Buy Before I Sell?
Buying and selling do not have to happen in one fixed order, but the timing needs a plan.
Get the Answer
Let’s start with a conversation
Tell me what you’re trying to accomplish.
You don’t need to know which loan program you need. You don’t need to have every document ready. And you don’t need to fill out a full mortgage application just to start a conversation.
Tell me a little about what you’re working toward, and I’ll be in touch soon.
No SSN, asset information or full loan application required to start the conversation.